The income tax base is one of the most consequential figures in any company’s financial life yet it remains widely misunderstood, even among experienced business owners. Get this number wrong, and you’re either overpaying or, worse, exposing your company to penalties during a tax audit. Understanding how the income tax base is calculated, what it includes, and how different tax types define it is not optional knowledge, it’s a business essential.
At OMK, a certified legal accounting office with deep experience in Saudi tax law, we work with companies of all sizes to ensure their tax base is calculated accurately, legally, and strategically. The difference between a well-structured tax position and a poorly managed one often comes down to how well a business understands the rules and that’s precisely where OMK’s expertise delivers real, measurable value.
The Income Tax Base in Companies
When we talk about the income tax base inside a corporate structure, we’re referring to the net taxable income derived after all allowable deductions and adjustments have been applied to gross revenue. This is not simply what a company earns — it’s what the tax authority considers to be the true economic gain subject to taxation. Here’s what’s interesting: two companies with identical revenues can have dramatically different tax bases depending on their expense structures, depreciation schedules, and loss carryforwards.
Saudi tax regulations, particularly under the Zakat, Tax, and Customs Authority (ZATCA) framework, specify which revenues are included in income and which deductions are permitted. Non-Saudi shareholders, for example, are subject to income tax on their proportional share of taxable income, while Saudi and GCC shareholders are subject to Zakat. This dual system makes it critical for companies to correctly identify their ownership structure before even beginning to calculate their tax base.
Understanding income and tax as interconnected concepts — not separate concerns — is central to this process. The types of income a company generates, whether from core operations, investments, capital gains, or royalties, each carry different treatment under income tax regulations.
The Tax Base in Value Added Tax (VAT)
- The VAT tax base is the total value of taxable supplies of goods and services before VAT is applied.
- It includes the sale price, any additional charges such as delivery or installation fees, and other amounts received as part of the transaction.
- Discounts that are given at the time of sale and reflected on the invoice can reduce the tax base.
- Imports are also subject to VAT, and their tax base includes customs value plus any applicable customs duties.
- The standard VAT rate in Saudi Arabia applies at 15% on top of the calculated base the base itself must be accurately reported on every tax invoice.
The Tax Base in Zakat
- The Zakat base for Saudi and GCC shareholders is determined using the net assets method or the profit method, whichever produces a higher result.
- It includes items such as retained earnings, net income for the year, non-Saudi loans used in the business, and certain reserves.
- Fixed assets and long-term investments are generally deducted from the Zakat base since they are considered productive assets.
- Adjustments for intercompany transactions, related-party balances, and unrealized gains are frequently required.
- Unlike income tax, Zakat is assessed at a flat rate of 2.5% on the calculated base — making accurate base determination directly equivalent to cost control.
The Importance of Legitimate Tax Base Planning
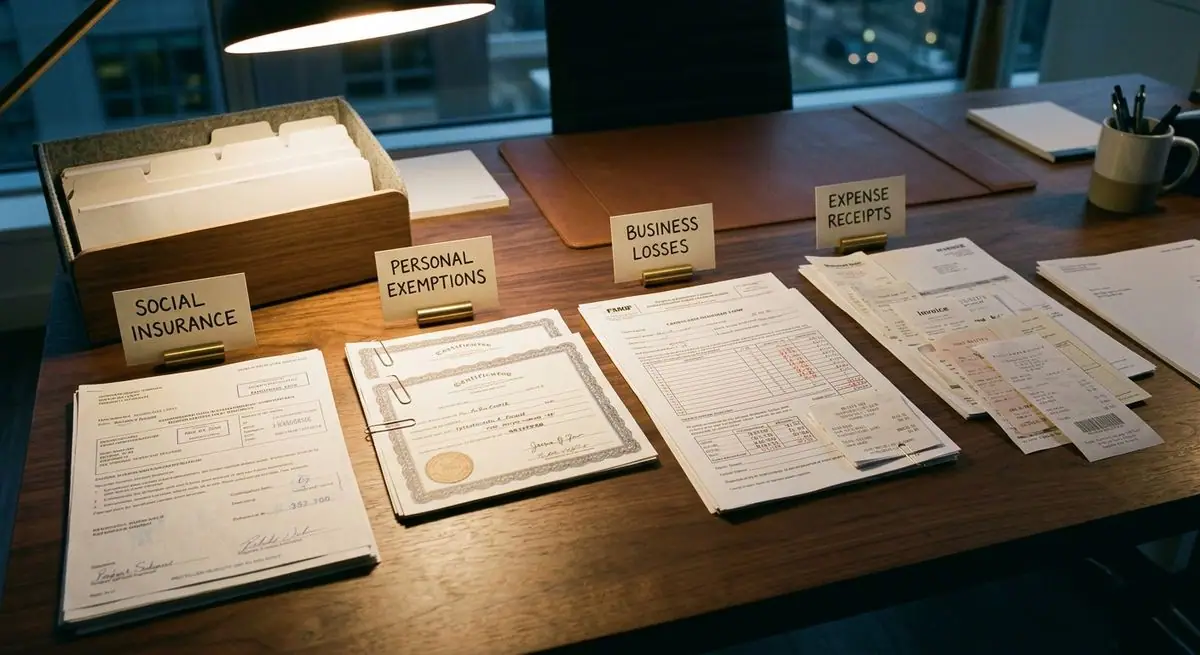
- Accurate base calculation prevents over-assessment by the tax authority, which can drain cash flow unnecessarily from a business that is actually profitable but tax-inefficient.
- Lawful planning around allowable deductions — such as research expenses, employee benefits, and depreciation — directly reduces the taxable base without any legal risk, provided the supporting documentation is in order.
- Companies that understand income tax regulations are better positioned to structure contracts, investment activities, and financing arrangements in a way that does not artificially inflate their taxable income.
- Proactive planning reduces the risk of disputes with ZATCA during annual filings or field audits — a situation that can be costly in both time and professional fees if not handled by an experienced certified accounting office like OMK.
- Loss carryforward provisions allow prior-year losses to offset future taxable income, reducing the base in subsequent years — but only if those losses were correctly recognized and filed in the first place.
- Regular review of the tax base in light of changes to income tax regulations ensures that companies are not applying outdated rules, which is a more common problem than most financial managers would like to admit.
The Income Tax Base in IAS 12
Under IAS 12 — the international accounting standard governing income taxes — the concept of the tax base takes on a specific technical meaning that differs from how it’s used in daily tax compliance conversations. The tax base of an asset is the amount that will be deductible for tax purposes against any taxable economic benefits that will flow to the entity when it recovers the carrying amount of that asset. The tax base of a liability, on the other hand, is its carrying amount less any amount that will be deductible for tax purposes in respect of that liability in future periods.
What this creates in practice is the concept of temporary differences — situations where the accounting carrying value of an asset or liability differs from its tax base. These differences give rise to either deferred tax assets or deferred tax liabilities, which must be recognized on the balance sheet. Most people overlook how significantly these deferred tax balances can affect a company’s reported financial position and effective tax rate, particularly in capital-intensive industries with large fixed asset bases.
OMK’s legal accounting office applies IAS 12 rigorously when preparing financial statements, ensuring that clients not only comply with Saudi tax law but also present accurate, audit-ready financial reports. The relationship between types of income, temporary differences, and the income tax base is complex — but navigating it correctly is exactly what distinguishes a competent accounting office from a basic bookkeeping service.
What Is Meant by the Tax Base?
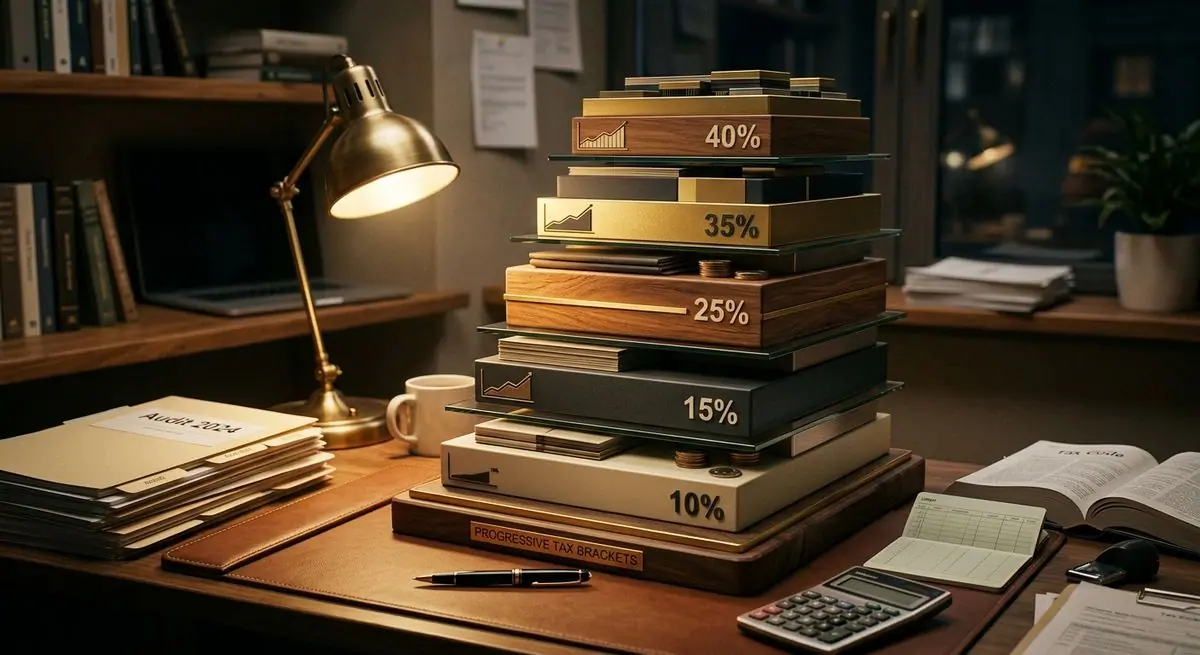
Stripped back to its core, the tax base is the quantity or value upon which a tax rate is applied to produce the actual tax liability. Think of it as the foundation of the entire tax calculation — if the foundation is incorrectly measured, every number that follows is wrong. For income tax specifically, the base is net taxable income. For VAT, it’s the value of taxable supplies. For customs duties, it’s the customs value of imported goods. For Zakat, it’s the calculated zakatable wealth.
The reason this definition matters so much in practice is that taxpayers often confuse the base with the tax itself. The tax base is not what you pay — it’s what you pay on. A company with a taxable income base of SAR 2 million pays 20% of that figure as income tax, arriving at SAR 400,000 in tax due. Reduce the base to SAR 1.5 million through legitimate deductions, and the tax due falls to SAR 300,000. The lever is always the base.
Types of Tax Base
Different types of tax in the Saudi system each have their own distinctly defined base, and conflating them creates serious filing errors. Understanding types of tax and the base applicable to each is a foundational skill for any financial manager or business owner operating in the Kingdom.
1. Income Tax
- Applied to non-Saudi shareholders’ proportional share of company profits.
- The base is net taxable income after allowable deductions under the income tax regulations.
- The standard rate is 20% for most commercial activities.
- Capital gains on the sale of shares in Saudi companies are also included in the income calculation under specific conditions.
- Withholding tax provisions apply to certain payments made to non-residents, and the base for withholding is the gross payment amount.
2. Value Added Tax (VAT)
- The base is the consideration received for taxable supplies, net of any VAT-inclusive discounts clearly stated on the invoice.
- Services rendered within Saudi Arabia are subject to VAT even if the service provider is based abroad, under reverse charge rules.
- Zero-rated and exempt supplies do not contribute to output VAT but must still be reported accurately in periodic returns.
- Input VAT recovery is only permitted on purchases linked to taxable activity — the allocation of mixed-use input tax requires careful proportional calculation.
3. Customs Duties
- The tax base for customs is the customs value of the imported goods, typically determined using the transaction value method per WTO rules.
- Additional charges such as insurance and freight costs are included in the customs value.
- Anti-dumping duties and countervailing measures can alter the effective base significantly for certain product categories.
- Preferential trade agreements with certain countries can reduce the applicable duty rate applied to the base.
4. Zakat
- The Zakat base includes net working capital, long-term financing from non-Saudi sources, and current-year net income.
- Adjustments for capital expenditures and specific exempt assets are applied before the final base is confirmed.
- The filing must reconcile with the company’s audited financial statements — discrepancies trigger ZATCA queries.
- Saudi shareholders and GCC-national shareholders are assessed for Zakat while non-Saudi shareholders face income tax on the same corporate profits.
How to Calculate the Income Tax Base in Saudi Arabia
- Start with the company’s total gross revenue for the fiscal year as reported in the income statement.
- Deduct all allowable business expenses as defined under Saudi income tax regulations — these include salaries, rent, depreciation, and cost of goods sold, among others.
- Add back any non-deductible expenses that were charged in the accounts but are not permitted under tax law, such as certain entertainment costs or provisions that don’t meet the regulatory threshold.
- Account for any tax losses carried forward from prior years, which can be offset against current-year taxable income up to the limits specified by ZATCA.
- Allocate the resulting net taxable income between Saudi/GCC shareholders (subject to Zakat) and non-Saudi shareholders (subject to income tax) based on ownership percentages.
- Apply the applicable tax rate — 20% for income tax — to the non-Saudi shareholders’ portion of the base to arrive at the final tax liability.
- Submit the completed return with supporting schedules through the ZATCA portal within 120 days of the fiscal year-end, ensuring all documentation is properly retained for potential audit.
The Difference Between the Tax Base and the Tax in Saudi Arabia
- The tax base is the calculated figure (net taxable income, taxable supply value, etc.) on which the tax rate is applied — it is not itself a payment.
- The tax is the monetary amount that results from applying the rate to the base — this is what actually gets paid to the authority.
- A company can have a large tax base but a low effective tax rate due to treaty benefits or incentives — conversely, a smaller base with no reliefs may produce a proportionally higher tax bill.
- The tax base changes every year based on business performance, expense patterns, and regulatory adjustments; the tax rate is generally fixed by law and changes only through legislative action.
- Errors in calculating the base carry penalties under ZATCA rules, whereas the rate itself is not something taxpayers control or dispute — meaning base accuracy is where all the professional effort should be concentrated.
- Voluntary disclosure of base calculation errors is treated more favorably than errors discovered during audit — another reason why working with a certified legal accounting office proactively is far better than dealing with corrections after the fact.
Frequently Asked Questions
What is the income tax base and how is it calculated in Saudi Arabia?
The income tax base is the net taxable income figure that results after subtracting all legally allowable deductions from a company’s gross revenue. In Saudi Arabia, this applies specifically to non-Saudi shareholders’ portion of company profits, calculated under the framework set by ZATCA. The process involves adding back non-deductible expenses, applying any permissible loss carryforwards, and allocating income correctly between shareholders subject to tax and those subject to Zakat. OMK’s certified accounting office handles this calculation regularly and can ensure your company’s base is correctly and defensibly determined.
What is the difference between the tax base and the tax amount itself?
Think of the relationship this way: the tax base is the measuring stick, and the tax is the result of applying a rate to that measurement. If your income tax base is SAR 1,000,000 and the rate is 20%, your income tax liability is SAR 200,000 — the base and the tax are two entirely different numbers serving two different purposes. Most disputes with tax authorities arise at the base level, not at the rate level, which is why getting the base right from the start is the most important task in tax compliance.
How does IAS 12 define the tax base of an asset or liability?
Under IAS 12, the tax base of an asset is the amount recoverable for tax purposes against future taxable income when the asset’s carrying value is realized. For a liability, it is the carrying amount minus any future tax deductions related to that liability. These definitions matter enormously because differences between accounting carrying values and tax bases create temporary differences, which must be recognized as deferred tax assets or liabilities on the balance sheet. OMK’s legal accounting office ensures that IAS 12 compliance is fully integrated into every set of financial statements we prepare.
The income tax base is not a bureaucratic formality — it is the single most important variable in determining how much tax your company actually owes. Every legitimate deduction, every correct income classification, every properly documented expense is an opportunity to ensure the base reflects your true taxable position, nothing more and nothing less. Businesses that treat tax base calculation as an afterthought consistently pay more than they should or find themselves exposed during audits. Don’t let that be your company. Contact OMK a trusted certified legal accounting office today to get a full review of your tax base, ensure compliance with Saudi income tax regulations, and build a tax position you can stand behind with complete confidence.