Understanding the financial statements of joint stock companies is one of the most practical skills any investor, analyst, or business owner can develop. These documents are not just regulatory formalities — they are detailed snapshots of a company’s financial health, revealing everything from profitability to long-term solvency. Getting comfortable with them takes time, but the payoff is enormous.
At OMK, where our advisory work spans a range of professional consulting services, we recognize that financial literacy is foundational to sound decision-making. Whether you are an individual shareholder or a corporate stakeholder, knowing how to interpret the financial statements of joint stock companies helps you ask sharper questions and make better-informed choices.
How to Analyze the Financial Statements of Joint Stock Companies
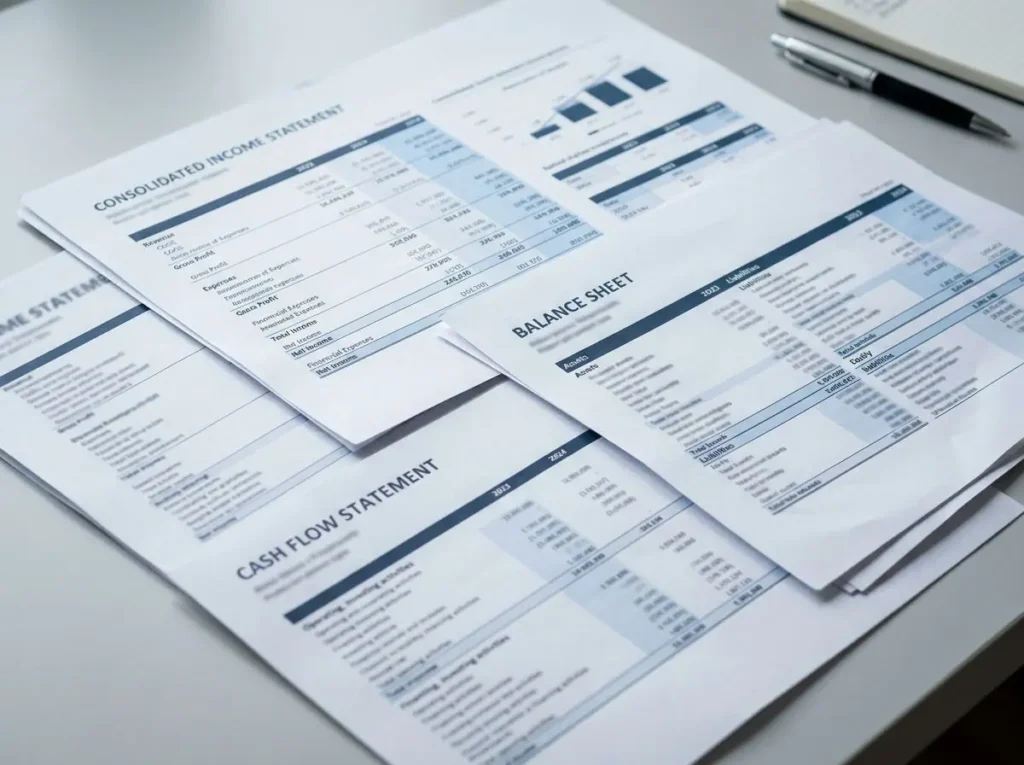
The financial statements of joint stock companies tell a story — and like any story, you need to read it in sequence and with context. Start with the income statement to understand revenue trends, then cross-reference those figures with the balance sheet to see how profits translate into actual assets or liabilities. The cash flow statement ties everything together, showing whether the company is genuinely generating cash or just reporting accounting profits.
What’s interesting here is that most amateur investors focus almost entirely on net income and ignore cash flow entirely. That is a costly mistake. A company can show healthy profits on paper while simultaneously running out of cash to pay its suppliers. Real financial analysis means triangulating across all three core statements, not just skimming the headline numbers.
Financial statement analysis also requires benchmarking. Comparing a company’s ratios against industry averages — or against its own historical data — gives you a much cleaner picture than looking at absolute numbers in isolation. This is where tools like ratio analysis and trend analysis become genuinely useful, which we will cover in detail below.
Types of Financial Data
Before diving into tools and techniques, it helps to understand what each major document actually contains. Joint stock companies are required to prepare several distinct financial reports, each serving a different analytical purpose.
The Balance Sheet
- Lists all company assets — both current (cash, receivables, inventory) and non-current (property, equipment, intangibles)
- Shows total liabilities, broken into short-term obligations and long-term debt
- Reflects shareholders’ equity, which is the residual value after subtracting liabilities from assets
- Provides a point-in-time view — typically at the end of a fiscal quarter or year
- Helps analysts assess liquidity ratios such as the current ratio and quick ratio
Revenue and Income
- Gross revenue represents total sales before any deductions
- Gross profit is calculated after subtracting the direct cost of goods sold
- Operating income removes overhead expenses, giving a clearer view of core business performance
- Net income is what remains after taxes, interest, and all other charges
- Earnings per share (EPS) is derived from net income and is especially important for publicly traded joint stock companies
Liabilities and Debt
- Current liabilities include accounts payable, short-term loans, and accrued expenses due within one year
- Long-term liabilities cover bonds, mortgages, and multi-year loan obligations
- The debt-to-equity ratio — derived from these figures — signals how aggressively the company is leveraged
- Contingent liabilities (potential future obligations like lawsuits) may appear in footnotes and should not be ignored
- Understanding the liability structure is critical for assessing default risk and financial resilience
Learn about: Types of Financial Statements in Accounting
Tools for Analyzing the Financial Statements of Joint Stock Companies
- Ratio Analysis — The most widely used tool. Liquidity ratios, profitability ratios, leverage ratios, and efficiency ratios each shed light on a different dimension of performance. Financial statement analysis built on ratios allows comparisons across time and across competitors.
- Horizontal Analysis — Compares line items across multiple periods (year-over-year or quarter-over-quarter) to identify trends. A sudden spike in operating expenses, for example, becomes immediately visible.
- Vertical Analysis — Expresses each line item as a percentage of a base figure (total revenue for the income statement, total assets for the balance sheet). This standardizes data and makes cross-company comparisons more meaningful.
- Cash Flow Analysis — Examines operating, investing, and financing activities separately. A company consistently burning cash in operations but reporting profits is a major red flag.
- DuPont Analysis — Breaks return on equity (ROE) into its component drivers: profit margin, asset turnover, and financial leverage. It reveals why a company is performing the way it is, not just that it is.
- Trend Forecasting — Uses historical data patterns to project future performance. This is especially useful when evaluating whether current valuations are justified.
You may also want to know about: Financial Statement Filing Requirements
Which Companies Are Required to File Their Financial Statements?
- All publicly listed joint stock companies operating on a regulated stock exchange
- Private joint stock companies that exceed a legally defined threshold of shareholders or capital
- Companies that have issued bonds or other debt instruments to the public
- Holding companies with subsidiaries, regardless of whether the parent is publicly listed
- Any joint stock entity operating in a regulated industry such as banking, insurance, or telecommunications
- Foreign joint stock companies with registered branches or significant operations in the jurisdiction
Here’s the thing — many smaller joint stock companies mistakenly believe they fall below reporting thresholds when they do not. Regulatory bodies have progressively tightened definitions over recent years, expanding the scope of mandatory disclosure requirements.
Legal Deadlines for Filing Financial Statements
- Quarterly Reports — Most jurisdictions require interim financial statements to be submitted within 45 days of the end of each fiscal quarter.
- Annual Reports — Full-year audited financial statements are typically due within 90 days of the fiscal year-end, though some regulatory bodies allow up to 120 days for complex entities.
- Extraordinary Disclosures — Material events (mergers, significant losses, executive changes) must be disclosed within 24 to 72 hours in most regulated markets.
- Auditor Sign-off Deadlines — The external audit must be completed and signed before submission; companies should engage auditors at least two months before the filing deadline.
- Shareholder Meeting Alignment — Annual financial statements must typically be approved by the board and presented to shareholders at the annual general meeting before or shortly after regulatory submission.
Learn about: Steps to Review Financial Statements
Conditions for Filing Financial Statements
- Statements must be prepared in accordance with the applicable accounting standards — either International Financial Reporting Standards (IFRS) or locally mandated equivalents
- An independent external auditor must review and issue a formal opinion on the statements before filing
- All figures must reconcile across documents — any discrepancy between the balance sheet and cash flow statement triggers regulatory scrutiny
- Electronic submission through the relevant regulatory portal is now mandatory in most jurisdictions
- The filing must include comparative figures from the prior period to enable trend assessment
- The company’s authorized signatory (typically the CFO and CEO) must formally certify the accuracy of all submitted data
Required Documents for Filing
- Audited Financial Statements — Including the balance sheet, income statement, cash flow statement, and statement of changes in equity
- Independent Auditor’s Report — A formal opinion letter from the certified external auditor, including any qualifications or emphasis-of-matter paragraphs
- Notes to the Financial Statements — Detailed disclosures explaining accounting policies, significant estimates, and major transactions
- Board of Directors’ Report — A narrative summary of business performance, risks, and strategic outlook for the period
- Corporate Governance Declaration — Confirming compliance with applicable governance codes and listing requirements
- Signed Certification Forms — Executed by the CEO and CFO attesting to the completeness and accuracy of all submitted information
- Prior Period Comparative Data — Restated prior-year figures if any accounting policy changes were made during the current period
Mastering the financial statements of joint stock companies is not a one-time achievement — it is an ongoing practice that sharpens with every report you read and every ratio you calculate. The layers of information contained in these documents reward patient, methodical readers. If you are still building your confidence with financial statement analysis, start with the income statement, work your way to the balance sheet, and always finish with cash flow. OMK is here to support you with expert advisory resources and practical guidance every step of the way — reach out today and start making your financial analysis work harder for you.
Frequently Asked Questions
What is the main purpose of financial statements for joint stock companies?
The primary purpose is transparency — giving shareholders, creditors, regulators, and the public a reliable basis for evaluating the company’s financial position and performance. The financial statements of joint stock companies serve as the legal and commercial record of what a business earned, spent, owed, and owned during a specific period. Without them, capital markets simply could not function with any level of integrity or confidence.
Who is legally required to file financial statements?
Any entity structured as a joint stock company is generally subject to mandatory financial reporting requirements. This includes publicly listed companies, large private joint stock companies, and those operating in regulated sectors. The specific thresholds — whether based on capital, number of shareholders, or annual turnover — vary by jurisdiction, so it is always worth verifying with a qualified financial advisor or consulting a resource like OMK for jurisdiction-specific guidance.
What happens if a company misses its financial reporting deadline?
Late filings typically trigger financial penalties, which escalate the longer the delay continues. Regulatory bodies can also suspend trading in the company’s shares, issue public notices of non-compliance, and in severe cases, initiate legal proceedings against company officers. Beyond the legal consequences, missed deadlines erode investor confidence in ways that take years to rebuild — the reputational damage often outlasts the regulatory penalty itself.