Understanding how to prepare a cash flow statement is one of the most valuable financial skills any business owner or accountant can have. This document tells you, with complete clarity, where your money is coming from and where it is going — not in theory, but in hard numbers. Miss it, and you are flying blind.
At OMK, a certified public accounting office with deep experience in financial reporting and business advisory, we work with companies of all sizes to build accurate, compliant cash flow statements that serve as real decision-making tools — not just regulatory checkboxes.
What Is a Cash Flow Statement?
A cash flow statement is a core financial document that records all actual cash inflows and outflows a business experiences over a specific period. Unlike the income statement, which can include non-cash items like depreciation or accrued revenue, the cash flow statement deals strictly with real money — cash that entered or left the business. That distinction matters enormously when you are trying to assess whether a company can actually pay its bills.
What’s interesting here is that a business can show a healthy profit on paper and still struggle to meet payroll. That is the paradox the cash flow statement exposes. It bridges the gap between accounting profit and financial reality, giving management, investors, and lenders a transparent view of liquidity. Knowing how to prepare a cash flow statement correctly means understanding that gap and documenting it with precision.
What Movements of Money Make Up This Statement?
- Cash received from customers for goods sold or services rendered during the period.
- Cash paid to suppliers for inventory, raw materials, or outsourced services.
- Cash paid to employees as salaries, wages, bonuses, and related benefits.
- Cash received from the sale of long-term assets such as equipment, property, or investments.
- Cash paid to acquire new assets, including machinery, vehicles, or financial securities.
- Cash received from borrowing — loans from banks or bond issuances.
- Cash paid to repay debt principal or to distribute dividends to shareholders.
- Cash inflows from owner contributions or equity raises through stock issuance.
What Are the Components of a Cash Flow Statement?
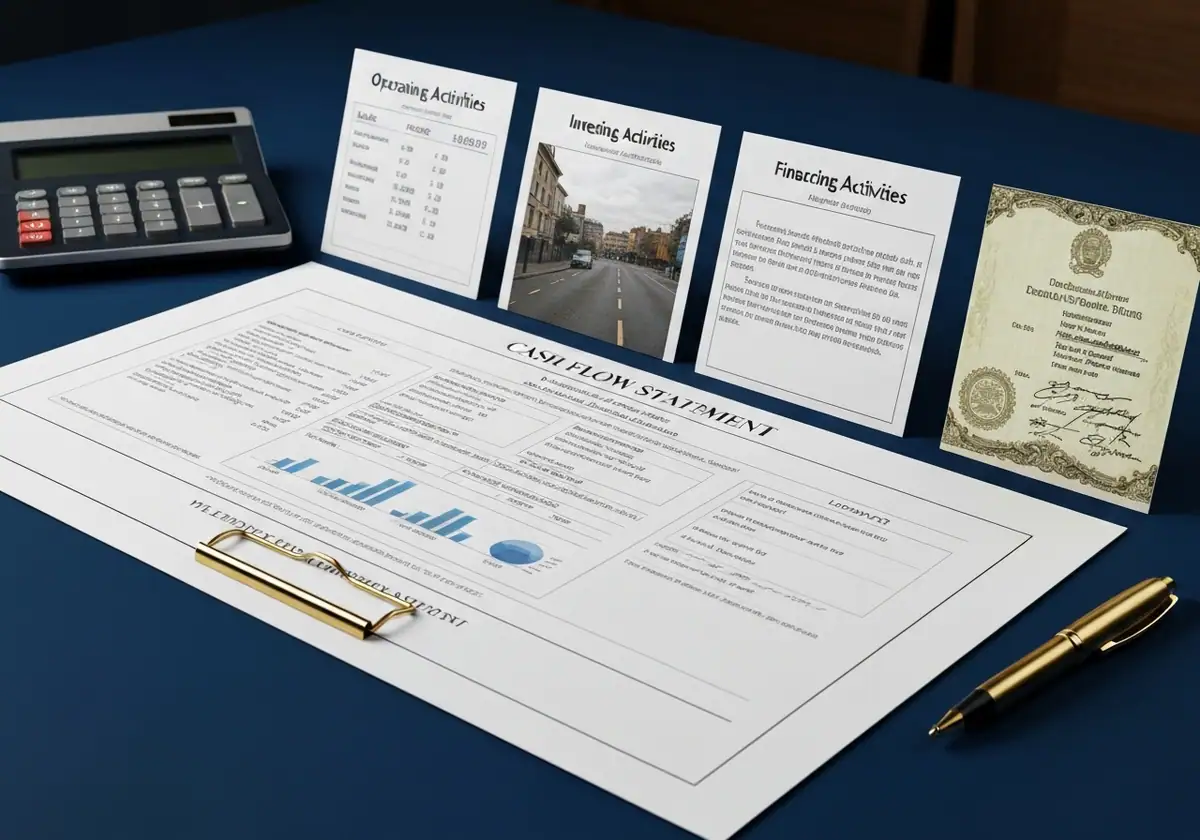
- Operating activities: cash generated or used by the core business operations, including customer receipts and supplier payments.
- Investing activities: cash flows related to the purchase and sale of long-term assets and investments.
- Financing activities: cash flows tied to borrowing, repaying debt, issuing equity, or paying dividends.
- Opening cash balance: the amount of cash and cash equivalents held at the start of the reporting period.
- Closing cash balance: the ending cash position after all inflows and outflows are accounted for.
- Non-cash adjustments: items such as depreciation and amortization that are added back when using the indirect method.
- Net change in cash: the overall increase or decrease in cash across all three activity categories combined.
What Is Net Cash Flow?
Net cash flow is the bottom line of your cash flow statement — the single number that tells you whether your business generated or consumed cash during the period. It is calculated by adding together the net cash from operating, investing, and financing activities. A positive figure means the business brought in more cash than it spent. A negative figure is not automatically catastrophic, but it demands explanation.
Here’s the thing: net cash flow is not the same as profit. A company might invest heavily in new equipment, producing a negative net cash flow for the quarter, while still being highly profitable. Context is everything. Understanding net cash flow in isolation is misleading — it must be read alongside the income statement and balance sheet. That integrated reading is exactly what the team at OMK helps clients perform when reviewing financial health across reporting periods.
Most people overlook the timing dimension. Cash flow is about when money actually moves, not when a transaction is legally recognised. A sale made in December may not be collected until February, and that gap can cause serious short-term liquidity stress even for profitable businesses.
What Is the Goal of a Cash Flow Statement?
- To give management a clear view of the company’s actual liquidity position at any point in time.
- To help investors assess whether the business generates enough cash to sustain and grow its operations independently.
- To allow lenders and creditors to evaluate repayment capacity before extending credit or refinancing existing debt.
- To identify patterns of cash generation or drainage across operating, investing, and financing activities.
- To support strategic decisions around capital expenditure, dividend policy, and debt management.
- To ensure regulatory compliance with accounting standards such as IFRS and local statutory requirements.
- To detect early warning signs of financial distress before they escalate into crises.
What Are the Steps to Prepare a Cash Flow Statement?
- Gather the comparative balance sheets for the beginning and end of the reporting period.
- Obtain the income statement for the same period to identify net income and non-cash items.
- Choose the method — direct or indirect — for presenting operating activities. The indirect method starts with net income and adjusts for non-cash items and working capital changes.
- Calculate cash flows from operating activities by adjusting net income for depreciation, amortisation, and changes in accounts receivable, inventory, and accounts payable.
- Calculate cash flows from investing activities by identifying purchases and sales of long-term assets and investments during the period.
- Calculate cash flows from financing activities by recording new borrowings, debt repayments, equity issuances, and dividends paid.
- Sum the net cash from all three sections and add it to the opening cash balance to verify it matches the closing cash balance on the balance sheet.
- Review and reconcile any discrepancies before finalising the statement.
When Is a Cash Flow Statement Prepared?
Most businesses prepare a cash flow statement at the end of each financial reporting period — typically quarterly and annually. Listed companies are generally required by law and stock exchange regulations to publish their cash flow statement as part of their periodic financial disclosures. For private businesses, the frequency may depend on lender requirements, internal management needs, or the terms of a financing agreement.
That said, many well-run organisations prepare internal cash flow projections on a monthly or even weekly basis. A forward-looking cash flow forecast is not the same document as the historical statement, but the two are closely related. The historical statement feeds the assumptions used in the forecast. At OMK, our certified accounting professionals help clients build both — the historical record and the forward projection — so they always know where they stand.
Can you afford to wait until year-end to discover you have a liquidity problem? Most businesses cannot. That is precisely why frequent preparation of cash flow analysis is considered best practice, not just a compliance exercise.
Types of Cash Flows
The three categories of cash flows each reflect a different dimension of how a business operates, grows, and funds itself. Operating flows show the engine — whether the core business generates real cash. Investing flows show ambition — whether the company is building capacity for the future. Financing flows show the capital structure — how the business is funded and how it rewards or repays its capital providers.
Cash Flows from Operating Activities
- Cash collected from customers for products sold or services delivered.
- Cash paid to employees as wages and salaries.
- Cash paid to suppliers for goods, materials, and operating services.
- Cash paid for rent, utilities, insurance, and other overhead expenses.
- Income taxes paid in cash during the period.
- Interest received on short-term investments or bank deposits held for operational purposes.
Cash Flows from Investing Activities
- Cash paid to purchase property, plant, and equipment.
- Proceeds received from selling fixed assets or disposing of subsidiaries.
- Cash paid to acquire shares or stakes in other companies.
- Cash received from the repayment of loans previously extended to third parties.
- Cash paid for intangible assets such as patents, licences, or software development.
Cash Flows from Financing Activities
- Cash received from issuing new shares or raising equity capital.
- Proceeds from bank loans, bonds, or other borrowing instruments.
- Cash paid to repay the principal portion of loans and long-term debt.
- Dividends paid in cash to shareholders during the period.
- Payments made to buy back the company’s own shares.
Common Mistakes When Preparing a Cash Flow Statement
- Confusing accrual-based revenue with actual cash received — a sale is not cash until it is collected.
- Failing to properly classify items between operating, investing, and financing sections, which distorts the picture each category is meant to show.
- Omitting non-cash investing and financing transactions that must be disclosed separately, such as assets acquired through finance leases.
- Double-counting items that appear in more than one section due to poor reconciliation with the balance sheet.
- Using the wrong opening cash balance, which causes the closing balance to fail reconciliation.
- Ignoring bank overdrafts when defining cash and cash equivalents at the start and end of the period.
- Treating interest paid inconsistently across periods, which creates comparability problems in multi-year analysis.
Goals of a Cash Flow Statement
- To provide a reliable basis for evaluating the company’s ability to generate positive cash flows in future periods.
- To reveal the relationship between profitability and cash generation, exposing gaps that the income statement alone cannot show.
- To support comparison across companies and industries, since cash flows are harder to manipulate than profit figures.
- To assist management in planning debt repayment schedules and capital investment programmes.
- To give auditors and regulators a verifiable trail of actual money movement throughout the business.
- To serve as the foundation for financial modelling, business valuation, and merger or acquisition due diligence.
Frequently Asked Questions about How to Prepare a Cash Flow Statement
What is the difference between a cash flow statement and an income statement?
The income statement reports revenues and expenses on an accrual basis, meaning it records transactions when they occur, regardless of when cash actually changes hands. The cash flow statement, by contrast, records only actual cash received and paid. A business can be profitable on the income statement while experiencing a cash shortage — and that is exactly why both documents are essential to a complete financial picture.
How often should a business prepare a cash flow statement?
Formal cash flow statements are typically prepared quarterly and annually for reporting purposes. However, understanding how to prepare a cash flow statement on a rolling monthly basis is considered best practice for active financial management. High-growth businesses, those servicing significant debt, or companies in seasonal industries benefit enormously from monthly or even weekly internal cash flow tracking. OMK’s accounting team can help you set up the right reporting cadence for your business size and complexity.
What are the most common mistakes when preparing a cash flow statement?
The most frequent errors include misclassifying transactions between the three activity sections, failing to reconcile the closing cash balance with the balance sheet, and incorrectly treating non-cash items. Many small businesses also overlook the disclosure requirements for non-cash financing transactions. Working with a certified public accounting office like OMK significantly reduces the risk of these errors and ensures your statement meets professional and regulatory standards.
Mastering how to prepare a cash flow statement is not just an accounting task — it is a strategic capability. When done correctly, this document becomes one of the most powerful tools in your financial toolkit, revealing the true health of your business beyond what profit figures alone can show. Every business owner, CFO, and finance manager should treat it with the same seriousness as the balance sheet or income statement.
If you want to get this right — whether you are building your first statement or improving an existing process — reach out to OMK. As a certified public accounting office with proven expertise in financial reporting, we are ready to help you prepare accurate, insightful cash flow statements that genuinely support your business decisions.