Understanding long-term financing sources is one of the most important steps any business owner or financial manager can take before making major investment decisions. These sources provide the capital backbone that allows companies to grow, expand, and survive economic cycles without constantly scrambling for cash. Getting this wrong — or ignoring it entirely — can quietly kill a business that looks healthy on the surface.
At OMK, a certified accounting office with deep experience in corporate finance advisory, we work regularly with clients who need clear, practical guidance on funding structures. Whether you’re launching a new project or restructuring an existing one, knowing which financing options fit your situation is not optional — it’s essential.
What Are Long-Term Financing Sources?
Long-term financing sources refer to funding mechanisms that provide capital for periods typically exceeding one year — and often stretching five, ten, or even twenty years into the future. These are not quick fixes or revolving credit lines. They are structural commitments that shape how a company is capitalized, how it shares risk, and how it plans its future investments.
The classic examples include equity issuance, long-term bank loans, corporate bonds, retained earnings, and mortgage financing. Each of these carries its own cost, risk profile, and repayment structure. What’s interesting here is that many business owners instinctively reach for bank loans when they think about long-term funding — but that’s only one piece of a much larger picture.
These sources are fundamentally different from short-term instruments because they are tied to strategic rather than operational needs. You don’t use a twenty-year bond to cover next month’s payroll. You use it to build a factory, acquire a competitor, or invest in technology infrastructure that won’t pay off for years. That distinction matters enormously when you’re sitting with a financial advisor at OMK mapping out a capital plan.
Corporate Financing Sources
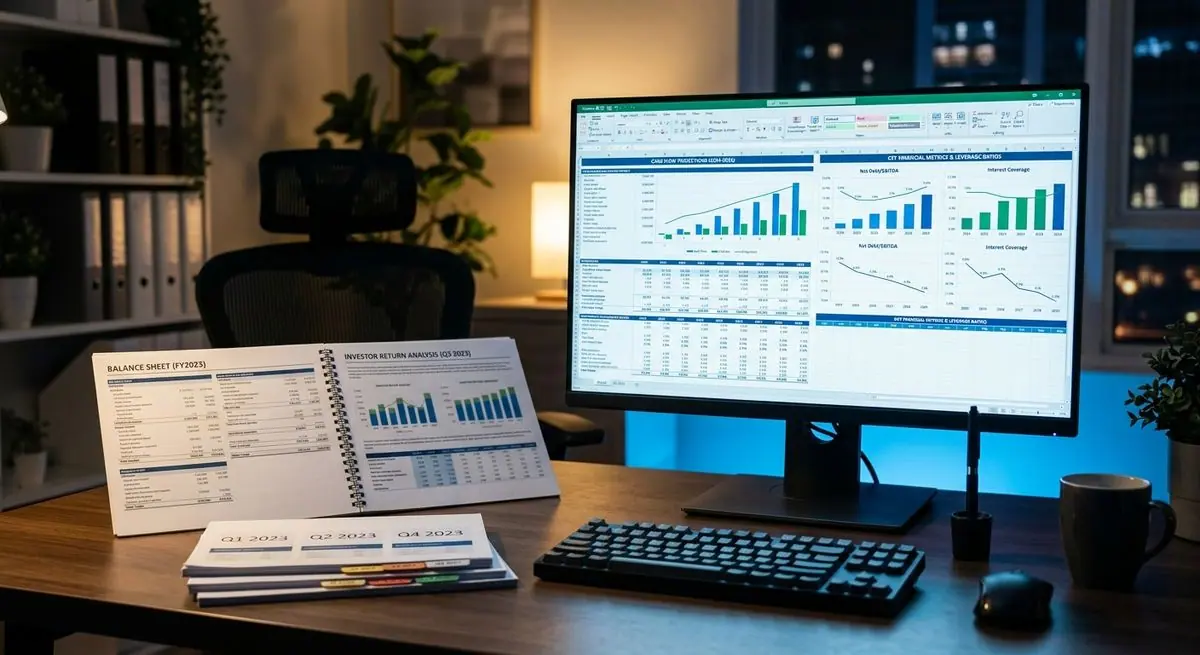
- Equity financing — Raising capital by issuing shares to investors, either through public markets (IPO) or private placements. This dilutes ownership but carries no repayment obligation.
- Long-term bank loans — Formal credit agreements with financial institutions, typically secured against assets, with fixed or variable interest rates and structured repayment schedules.
- Corporate bonds — Debt instruments issued to the public or institutional investors, paying a fixed coupon over a defined period before returning the principal at maturity.
- Retained earnings — Profits that the company chooses not to distribute as dividends but reinvests back into the business. This is the cheapest source of internal long-term financing.
- Mortgage loans — Loans secured specifically against real estate or property assets, widely used in capital-intensive sectors like manufacturing and hospitality.
- Leasing agreements — Long-term arrangements where a company uses assets (equipment, vehicles, facilities) without owning them outright, preserving cash while accessing productive resources.
- Venture capital and private equity — External investors who provide substantial funding in exchange for equity stakes, often bringing operational expertise alongside the capital.
- Development finance institutions — Government-backed or multilateral lenders offering concessional loans or guarantees for strategic economic projects.
The Importance of Long-Term Financing
- It provides the financial stability necessary for executing multi-year business plans without constant refinancing pressure.
- Long-term financing allows companies to invest in fixed assets — machinery, buildings, technology platforms — that generate returns over extended horizons.
- It smooths out cash flow volatility by aligning repayment schedules with the revenue streams that the financed assets are expected to generate.
- Access to diversified long-term financing types signals financial maturity to banks, rating agencies, and potential partners, improving the company’s overall creditworthiness.
- Retained earnings, as a form of internal long-term financing, reduce dependence on external creditors and preserve management control over strategic decisions.
- For growing businesses, having a clear long-term capital structure — one that OMK’s certified accounting office can help design and document — is often a prerequisite for attracting institutional investors.
- It supports research, development, and innovation cycles that simply cannot be funded on a short-term basis without destroying operational liquidity.
Characteristics of Long-Term Financing Sources
- Extended maturity period — Repayment extends well beyond one year, often spanning five to thirty years depending on the instrument and sector.
- Higher capital amounts — These sources typically involve larger sums than short-term credit, reflecting the scale of investment they are meant to support.
- Formal legal structure — Whether it’s a bond indenture, loan agreement, or shareholder contract, long-term financing is governed by detailed legal documentation.
- Cost of capital consideration — Each source carries a distinct cost — interest rates for debt, dividend expectations for equity — which must be weighed carefully against projected returns.
- Collateral or covenant requirements — Lenders and investors often require security interests in assets or impose financial covenants to protect their exposure.
- Impact on balance sheet — Long-term liabilities and equity appear on the balance sheet and directly affect leverage ratios, debt capacity, and financial risk perception.
- Strategic alignment — The choice among long-term financing types must match the company’s growth strategy, industry norms, and risk tolerance.
Benefits of Long-Term Financing Sources
- Capital preservation — Spreading repayment over years reduces the immediate cash burden on the business, protecting working capital for daily operations.
- Asset-liability matching — Funding long-lived assets with long-term capital creates a natural match between when you owe money and when assets generate income.
- Investor confidence — A company with well-structured long-term financing signals that it has credible future plans, which attracts further investment.
- Tax advantages — Interest payments on long-term debt are generally tax-deductible in most jurisdictions, lowering the effective cost of borrowing.
- Flexibility in growth planning — Management can commit to ambitious expansion without worrying that funding will evaporate mid-project.
- Reduced rollover risk — Unlike short-term financing, there’s no need to repeatedly renew credit lines at potentially unfavorable market conditions.
- Creditworthiness improvement — Successfully managing long-term debt builds a track record that opens doors to better financing terms in the future.
Drawbacks of Long-Term Financing
- Higher total interest cost — The longer the borrowing period, the more interest accumulates over time, even if the annual rate appears modest.
- Rigidity of commitment — Once locked into a long-term loan or bond structure, early repayment often triggers penalties, reducing financial flexibility.
- Equity dilution risk — Issuing shares to raise equity capital reduces existing shareholders’ ownership percentage and can shift control dynamics.
- Collateral requirements — Securing long-term loans against assets ties up those assets, limiting the company’s ability to use them in other financial arrangements.
- Complex documentation and compliance — Bond issuances, private equity deals, and institutional loans require extensive legal, financial, and regulatory work — exactly the area where OMK’s certified accounting office adds significant value.
- Market and interest rate risk — Variable-rate long-term loans expose borrowers to interest rate fluctuations that can significantly alter actual repayment costs.
- Covenant restrictions — Many long-term financing agreements include covenants that restrict dividends, additional borrowing, or asset disposal without lender approval.
The Difference Between Long-Term and Short-Term Financing
Here’s the thing — most people understand that long-term and short-term financing exist, but far fewer grasp why the distinction actually matters in practice. Short-term financing covers obligations due within twelve months: trade credit, overdraft facilities, short-term loans, and commercial paper. These are designed for liquidity management, not capital investment. You use them to bridge gaps, manage seasonal demand, or cover temporary shortfalls.
Long-term financing, by contrast, is a strategic decision. It determines how a company is fundamentally structured from a capital perspective. The cost is different, the risk is different, and the decision-making process should be far more deliberate. What most people overlook is that using short-term instruments to fund long-term assets — a classic mismatch — is one of the most common causes of financial distress in otherwise viable businesses.
The right balance between financing types depends on the industry, the company’s cash flow profile, asset base, and growth ambitions. There is no universal formula. That’s precisely why working with an experienced advisory team matters. OMK helps clients map out a financing structure that makes sense for their specific situation — not a generic template.
Determinants of Long-Term Financing
- Business size and maturity — Larger, established companies typically have more options and better terms than startups or small enterprises.
- Industry and asset intensity — Capital-heavy industries like manufacturing, energy, and real estate naturally require more long-term financing than service-based businesses.
- Profitability and cash flow — Lenders and investors scrutinize historical and projected cash flows to assess repayment capacity before committing funds.
- Existing debt levels — A company’s current leverage ratio directly affects how much additional long-term debt it can realistically carry.
- Market conditions — Interest rate environments, capital market depth, and investor appetite all influence which long-term financing types are available and at what cost.
- Management track record — Institutions financing long-term projects place enormous weight on the credibility and experience of the management team.
- Regulatory and tax environment — Local laws governing interest deductibility, foreign investment, and capital markets shape which instruments are most efficient in a given jurisdiction.
Frequently Asked Questions about Long-Term Financing Sources
What are the most common long-term financing sources available to businesses?
The most widely used long-term financing sources include long-term bank loans, equity issuance, corporate bonds, retained earnings, and leasing arrangements. Each serves a different purpose and suits different company profiles. Equity is typically favored when a business wants to avoid fixed repayment obligations, while bonds and loans are preferred when owners want to retain control. The best choice depends on the company’s financial position, growth plans, and the cost of each option — something OMK’s certified accounting office helps clients evaluate thoroughly.
How does long-term financing differ from short-term financing in practice?
Short-term financing covers immediate liquidity needs — usually within twelve months — while long-term financing funds strategic investments with payback periods stretching years into the future. In practice, this means different documentation, different risk assessments, and a completely different decision-making process. Mixing them up — using short-term credit to fund long-term assets — creates dangerous asset-liability mismatches that can destabilize otherwise sound businesses.
Can small businesses access long-term financing sources effectively?
Absolutely — though the path is different from large corporations. Small businesses often rely on government-backed loan programs, development finance institutions, or private investors willing to take equity stakes in exchange for patient capital. Retained earnings are also a powerful internal source that small businesses frequently underutilize. Working with a certified accounting office like OMK helps small business owners understand which financing types are realistically accessible and how to position their financials to qualify.
Choosing the right long-term financing sources is not a back-office accounting task — it’s a core strategic decision that shapes everything from risk exposure to growth trajectory. Done well, it gives a business the runway it needs to build something lasting. Done poorly, it creates obligations that compound quietly until they become impossible to manage. If you’re navigating funding decisions and want guidance grounded in real financial expertise, reach out to OMK’s certified accounting office. The right capital structure starts with the right conversation.